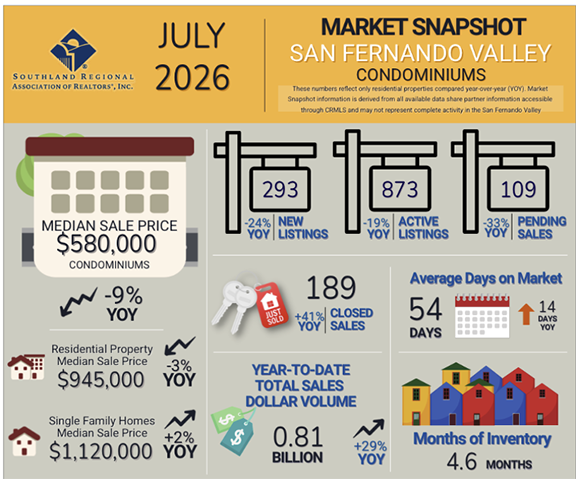
Condominium sales during July throughout the San Fernando Valley increased 41% compared to a year ago, as the income needed to purchase a median-priced home fell 13.3%, the Southland Regional Association of Realtors has reported.
An income of $147,000 was needed to qualify for an 80% loan of $464,000 on a San Fernando Valley median-priced condominium of $580,000.
The condo median price was down 9.4% from July 2025 and was only the fifth time in 30 months where the median price was below the $600,000 benchmark.
“Homebuyers, especially condominium buyers, are slowly adapting to the uncertainties of current market conditions,” said Nicole Stinson, President of the 10,000-member association. “Many of them are finding a decent inventory with a wider selection than a year or two ago and encountering a growing number of sellers who are willing to offer concessions.”
Local Realtors also helped close escrow on 567 single-family homes. That was up 5.8% from a year ago and the highest total in 12 months.
The median price of homes that changed owners last month came in at $1,120,000, an increase of 2.3% over July 2025. It was down from the June median price of $1,188,000, which set a record high.
The condominium median price of $580,000 was down 9.4% from a year ago, the association reported. The condo record high median price of $665,000 was set in April.
“Inventories of homes and condominiums remain elevated,” said Valerie Biletsky, the association’s Chief Executive Officer, “but are drifting lower than the record levels set a year ago. The enthusiasm to buy seen in 2025 is still there, but consumer confidence has been tempered by events in the Middle East and questions about the economy here at home.”
The association reported 1,870 single-family home active listings at the end of July. That was down 19.5% from a year ago. Similarly, the number of active condominium listings in July was 873, down 19% from 1,078 condo listings in July 2025, which was the only time in recent years to exceed the 1,000-listing benchmark.
SRAR’s income-to-loan guide for July found that an income of $147,000 was needed to qualify for an 80% loan of $464,000 on a San Fernando Valley median-priced condominium of $580,000. With the national average interest rate up to 6.35% during July – compared to January 2022’s 2.97% and below the 7.56% of December 2023 – the income needed to qualify fell 13.3% compared to a year ago. The monthly PITI — principal, interest, taxes and insurance payments — totaled $3,755.
For comparison, the California Association of Realtors reported that 19% of households statewide could afford to purchase the $916,750 median-priced home in the second quarter of 2026. That was down from 22% in the first quarter and up 17% from the second quarter of 2025.
A minimum annual income of $228,400 was needed to make monthly payments of $5,710, including principal, interest, taxes and insurance on a 30-year fixed-rate mortgage at a 6.54 percent interest rate. Thirty percent of homebuyers could afford the $670,000 median-priced condo or townhome. A minimum annual income of $166,800 was required to make a monthly payment of $4,170.
Compared with California, 40% of the nation’s households could afford to purchase a $434,900 median-priced single-family home in the second quarter of 2026.